Neobank Startups
Designing, Launching & Monetizing Digital Banking Platforms
Overview
Neobanks have redefined how consumers and businesses interact with financial services—delivering seamless digital experiences, embedded financial tools, and global accessibility.
But beneath the UI, every neobank is fundamentally a complex orchestration of banking partners, payment rails, compliance frameworks, and revenue engines.
The biggest misconception: "We'll figure out monetization later."
In reality, the success of a neobank is determined early—by how well its profit model, BaaS partner, and payments architecture are designed from day one.
This is where I operate: structuring neobanks that are bankable, compliant, and economically viable—not just well-designed apps.
Challenges Faced by Neobank Founders
Dependency on Banking Partners (BaaS)
Unclear or Weak Monetization Strategy
BaaS Provider Selection Risk
Regulatory & Compliance Burden
Payments & Card Infrastructure Complexity
Unit Economics & Scaling Challenges
Core Services for Neobank Startups
Neobank Structuring & Go-To-Market Design
BaaS Provider & Sponsor Bank Selection
Payments & Card Infrastructure Design
Compliance & Risk Frameworks
Vendor & Ecosystem Integration
Revenue Model Design
The four primary neobank profit engines
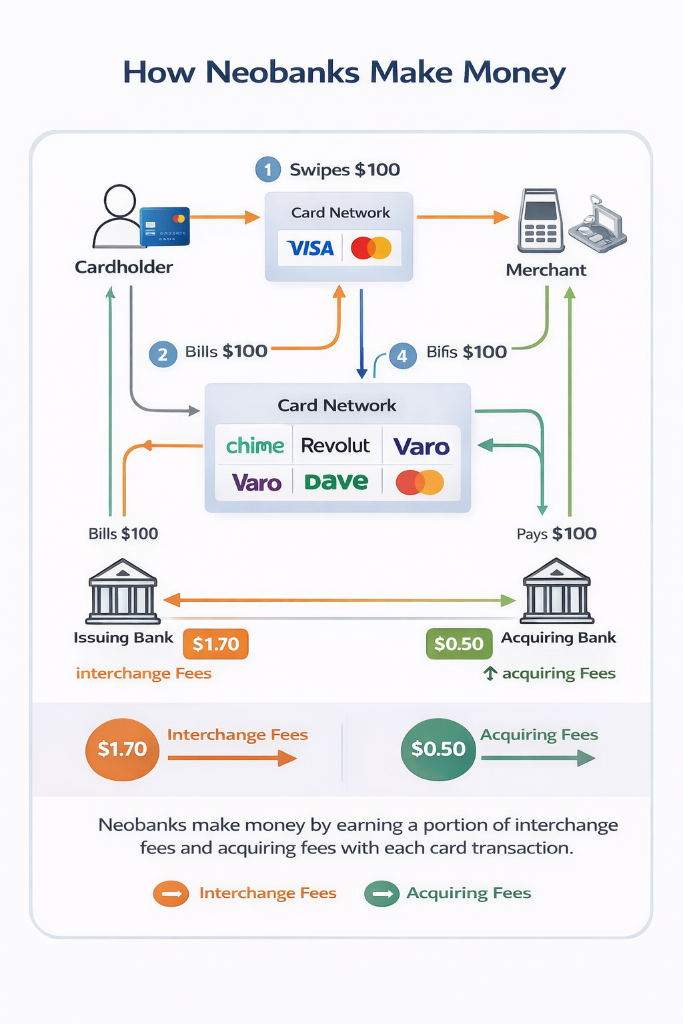
1. Interchange Revenue
Earned from debit/credit card usage, driven by transaction volume and customer engagement.
Strategy: Incentivize card usage and optimize spend categories.
2. Net Interest Margin (NIM) / Float
Revenue from customer deposits held with sponsor bank — the spread between what the bank earns and what is shared with the fintech.
Strategy: Maximize deposit balances and optimize sweep and treasury structures.
3. Subscription / SaaS Layer
Monthly fees for premium features: enhanced accounts, financial tools, perks (insurance, rewards, etc.).
Strategy: Tiered offerings with clear value differentiation.
4. Embedded Financial Products
Lending (BNPL, credit lines), FX/cross-border fees, wealth, crypto, or investment products, interchange+ affiliate revenue.
Strategy: Layer products over engaged user base to increase lifetime value (LTV).
Neobank Infrastructure & Revenue Stack
How to Think About the Neobank Stack
Layer 1 – Customer Experience Layer
Mobile app / web interface. Account onboarding and UX. Financial tools and engagement features.
Layer 2 – Application & Ledger Layer
Core ledger (accounts, balances, transactions). API orchestration across providers. Data and analytics layer.
Layer 3 – Payments & Card Infrastructure
Card issuing processor. ACH / wires / RTP / FedNow. Payment authorization and settlement.
Layer 4 – BaaS / Sponsor Bank Layer
Regulated bank providing accounts and compliance oversight. Holds customer funds. Interfaces with payment networks.
Layer 5 – Compliance & Risk Layer
AML/KYC systems. Fraud monitoring. Regulatory reporting.
Layer 6 – Revenue Layer (Overlay Across Stack)
Interchange (payments layer). NIM/float (banking layer). Subscription (UX layer). Embedded finance (cross-layer).
A neobank without a revenue architecture is just an expensive UI.
The difference between successful and failed neobanks comes down to choosing the right BaaS partner, designing resilient infrastructure, and embedding multiple revenue streams from day one.
I work with founders and operators to build neobanks that are:
- Bank-aligned and regulator-ready
- Economically viable at scale
- Positioned for long-term growth—not just launch
Build a neobank that actually makes money
Schedule ConsultationGet in Touch
Schedule a consultation or send a message directly.